
Russia's Road-Construction Machinery Market Slows Its Fall to 41% After Nine Months
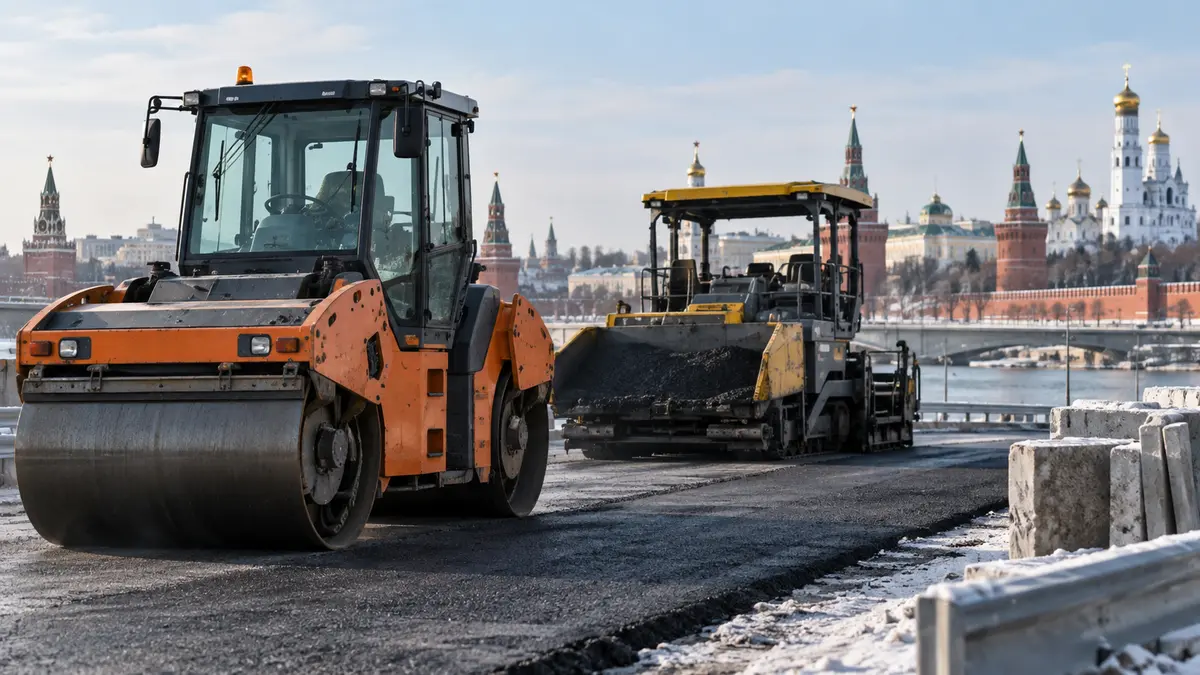
Sales of Russian-made road-construction machinery on the domestic market fell 41.3% year on year in January-September 2025 to 32.4 billion rubles, according to Rosspetsmash (Росспецмаш), the association that unites factories producing about 80% of all Russian road machinery. The pace of the decline is easing: it reached 45.4% in the first half, while September shipments dropped 25.7% year on year to 4 billion rubles.
A slower fall is not yet a recovery
Rosspetsmash stresses that the softer decline does not mean the situation has been righted. Producers of road-construction machinery have been in what the association calls a "stably difficult position" since the second half of 2024, when stocks of machines and equipment began growing rapidly both at dealers and at factories. The high key rate of the Central Bank, the association continues, led to a significant fall in investment activity among machinery makers and the consumers of their products.
Why demand collapsed
The main reason for the drop in demand, in the assessment of Maria Yarmalchuk (Мария Ярмальчук), chief executive of the National Association of Infrastructure Companies (NAIK), is the decline in road construction volumes and the difficult financial position of organizations in the sector. According to NAIK's research, since 2022 the residual volume of contracted but uncompleted work under state contracts for the construction, reconstruction and major repair of roads and engineered structures has been falling sharply. "The current financial position of road-and-bridge construction organizations does not allow them to ensure renewal of their road machinery fleets," Yarmalchuk says.
A second drag is structural: several categories of road machinery are either not produced in Russia at all or only in limited quantities - anti-segregation transfer vehicles, asphalt pavers, concrete pavers, road milling machines, recyclers and self-propelled soil-stabilization machines. Alexander Ruchiev (Александр Ручьев), shareholder and president of the Osnova (Основа) group, adds that the sharp slowdown in fleet renewal is a consequence of expensive leasing: high rates force contractors to postpone the purchase of new equipment.
The segment scoreboard
In unit terms, nine-month shipments tracked by Rosspetsmash fell across almost the entire product range:
- truck cranes: down 50%;
- pipelayer cranes: down 71%;
- telescopic handlers: down 86%;
- front loaders: down 42%;
- motor graders: down 35%;
- crawler bulldozers: down 57%;
- rollers: down 68%;
- skid-steer loaders: down 35%;
- excavators: down 27%.
Growth among the main segments was recorded in only two niches: crane-manipulators, up 24%, and backhoe loaders, up 38%. Sales of imported road machinery also declined in January-September, though at a slower pace than domestic output, estimates Dmitry Babansky (Дмитрий Бабанский) of SBS Consulting.
What the industry watches next
- Whether the bottom is behind: most experts surveyed by Kommersant believe the market has passed its lowest readings and is moving to a smoother decline.
- The resale of repossessed leasing equipment: in the first half, sell-offs of seized machines held back new-equipment shipments, and that peak has now largely passed, a market source says.
- Seasonality: the end of the year is traditionally the high season, when customers "spend down" annual budgets.
- Credit conditions: a gradual, if slow, decline in lending rates, and mortgage issuance in 2026 is expected to recover to the 2024 level, Babansky notes.
- Infrastructure spending through national projects in 2026, which could flow into road machinery demand, according to Sherpa Group.
Analysts keep a negative forecast for 2025 demand, and the market is likely to remain at low readings at least until 2028, a Kommersant source says. Alexandra Galaktionova (Александра Галактионова), chief executive of Sherpa Group, sketches the recovery scenario: if spending on the road segment grows more than planned during 2026 and the 2027-2028 budgets are not significantly revised in the autumn, a pickup in fleet renewal could come in the second half of next year.
Just Published

European housing prices and rents

Schneider–PTC: the industrial data integration test behind the deal

Avio USA starts work on its Virginia manufacturing site

One equity market, two currency measures

Russia’s draft budget raises spending and borrowing plans

Russia Sets the 2027 Minimum Wage at 28,935 Rubles, Up 6.8%, on the Way to 35,000 by 2030
Partner news digest
 Qatar LNG expansion: readiness, financing and the production test
 Pennon’s capital plan: turning finance into better water outcomes
 Italy’s diesel relief gap: taxes, price ceilings and implementation
 EU–China hybrid trade: from understanding to measurable implementation
 Schneider–PTC: the industrial data integration test behind the deal
 IKEA’s hybrid resale model: buyback, marketplace liquidity and furniture logistics
 Banking AI beyond the ranking: capability, execution and evidence of value
 Fishing labour beyond the product label: practical protection
 Rhenus and the Middle Corridor: terminals need coordinated connections
 Royal Mail restructuring: the test is reliable delivery
 Fuel Finder on Google Maps: when price transparency becomes useful competition
 Samsung’s memory profit surge: what the preliminary record explains
Leave a comment