
Record Price Tags: How Russia's Car Market Entered Winter 2025 at All-Time Highs
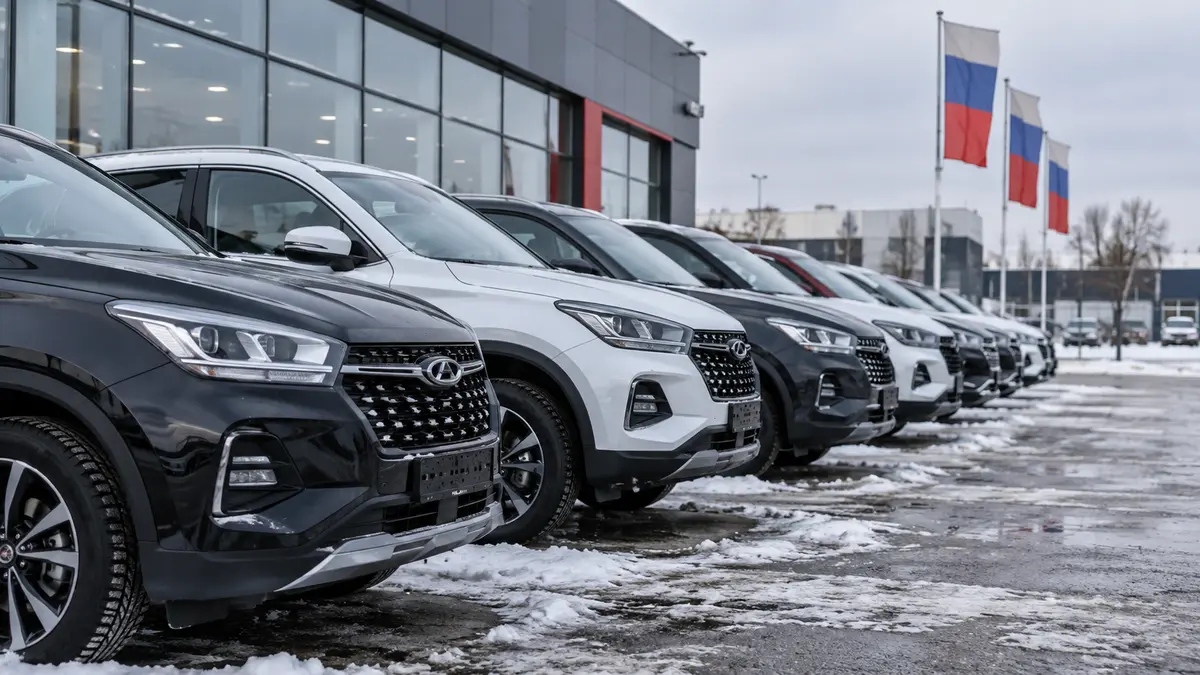
In October 2025 the Russian car market produced a paradox that dealers had been expecting for months: sales volumes jumped by more than a third in a single month, and at the same moment the average price of both a new and a used car reached the highest level ever recorded. Kommersant, citing calculations by Avtostat (Автостат), reported that the weighted average price of a new passenger car rose 2.2% month on month to 3.43 million roubles, while the used-car average climbed to 1.23 million roubles. Both figures were records, and both were set in a market rushing to buy ahead of an expected increase in the recycling fee and value added tax.
Two records in one month
The October numbers stand out even against a year of steady price growth. The weighted average price of a new passenger car in Russia reached 3.43 million roubles, up 2.2% on September and up 8% year on year, which Avtostat describes as the highest reading in the entire history of the market. The indicator is built from distributor recommended prices weighted by actual sales of each model and modification, so it tracks what buyers really paid for the basket of cars sold in the month rather than the sticker price of any single model.
The secondary market set its own record in parallel. The weighted average price of a used passenger car reached 1.23 million roubles in October, up 2.5% on the previous month and 3% above October 2024. Here the methodology differs: the used-car average is weighted by market volumes per model and production year, without splitting modifications, which makes it a cleaner read on the value of the existing fleet.
The demand spike behind the price records
Price records rarely arrive alone, and October 2025 was no exception. New passenger car sales jumped 35% relative to September, to 165.7 thousand units, the strongest monthly result since November 2024. A demand spike of that size in a market that had spent most of the year constrained by expensive credit points to a calendar effect: buyers pulled purchases forward in expectation of a repricing.
The trigger named by market participants is the anticipated revision of the recycling fee together with an increase in value added tax. Alexander Vasilyev (Александр Васильев), director of the automotive industry group at DRT (ДРТ), says distributors and dealers began lifting prices against the backdrop of the hype caused by the expected review of price tags. In his formulation, the recycling fee directly influences the price of a car because it forms the vehicle's cost for the importer and for the consumer. When the market expects that cost to rise, list prices move first and the fee change merely confirms them.
The fee as a price floor
The mechanism matters for reading the records correctly. A recycling fee is not a marginal surcharge; it enters the importer's landed cost and therefore the minimum price at which a car can be sold without loss. An expected increase works like a forward price floor: sellers have no incentive to discount below a level that will soon become their cost, and buyers who need a car now have no incentive to wait. The result is a compressed window in which demand accelerates and discounts vanish at the same time.
Discounts disappear, credit subsidies shrink
The second force behind the October average was the quiet withdrawal of the incentives that had held transaction prices below list prices for much of the year. Nikolai Ivanov (Николай Иванов), director of the new car sales department at Rolf (Рольф), explains the increase by the gradual winding down of discount offers and by brands cutting their credit subsidisation programmes. When a manufacturer stops paying part of the loan interest, the monthly payment rises and the effective price of the car rises with it, even if the sticker never changes.
This channel is easy to miss in headline data because it operates below the list price. A market can show stable recommended prices while the average transaction price climbs simply because the gap between the two narrows. October 2025 combined that narrowing with an outright rise in stickers, which is why the monthly jump in the weighted average was so pronounced.
Shortages: the models that vanished from stock
The third force was scarcity. Ivanov notes that the sharp rise in demand produced deficits across the entire line-up of the Jetour brand and in individual models of Geely and Chery. The parallel import channel showed its own gaps: shortages were observed among Mitsubishi models, the BMW X6 and X7 and the Skoda Kodiaq. A deficit removes the last layer of price competition at dealer level, because a showroom with no stock has nothing to discount and a buyer with an urgent need has nowhere to go.
Scarcity also changes the composition of what is left on the lot. When the affordable configurations sell out first, the remaining inventory is skewed toward higher trims and higher prices, and the weighted average inherits that skew. This is where the shortage effect blends into the mix effect described by other market participants.
The mix effect: a more expensive basket
Ilya Petrov (Илья Петров), director of retail sales at Avilon (Авилон), adds that part of the October increase in the average price is connected with the growing share of more expensive models, both in parallel import and in the line-ups of Chinese brands. A weighted average moves when the basket moves, and in October the basket shifted upmarket: imports from China in higher trims and parallel-imported premium models occupied a larger slice of sales.
The mix effect is structural rather than episodic. Even if every individual model held its price, a market in which the cheap end sells out and the expensive end keeps selling will print a rising average. Combined with the fee-driven floor and the withdrawal of discounts, it explains why the October record was broad rather than confined to one segment.
The used market's own record
The secondary market's record carries a separate message. At 1.23 million roubles, the average used car became 3% more expensive year on year, and the monthly increase of 2.5% shows that the same pre-hike urgency reached buyers who were not buying new metal at all. A customer who cannot afford a new car at a record price does not stop needing transport; they move to the used lot, bid up its prices and set a record there too.
Dmitry Yarygin (Дмитрий Ярыгин), deputy head of the analytics department at Avtostat, frames the consequence bluntly: having sold a used car today, it is difficult to count on buying a new car of a similar class, not least because of new-car prices. By the weighted averages, he says, the gap between the two markets exceeds 2 million roubles.
Why the gap breaks the trade-in ladder
That gap is the mechanism by which a new-car price record transmits into the used market and then feeds back. In a healthy market, the trade-in value of an old car covers a meaningful share of a comparable new one, and the upgrade ladder keeps both markets liquid. When the spread widens beyond 2 million roubles, the owner of a three-year-old car can no longer step up without adding sums that approach the price of a second used car, so part of demand stays in the secondary segment and pushes its prices further.
The ten-month picture
Zooming out from the record month, the January-October averages tell a more measured story. The weighted average price of a new passenger car over the ten months rose 3.5% relative to the same period of 2024, to 3.23 million roubles. Used cars over the same period actually became 0.9% cheaper on average, at 1.16 million roubles. The contrast is instructive: for most of 2025 the secondary market was deflating in annual average terms, and only the autumn surge carried its October point to a record.
In other words, the used-car record is a late-year turn rather than a year-long trend, while the new-car record sits on top of a steady annual climb. That asymmetry is exactly what a pre-hike demand spike should look like: the segment with the coming cost shock reprices first and hardest, and the substitute segment follows with a lag.
What dealers expect before the New Year
The participants quoted by Kommersant expect the climb to continue into December, but gradually. Petrov believes smooth price growth will most likely persist until the end of the year despite traditional pre-New-Year promotions and dealer stimulus offers. Ivanov is more specific: prices will certainly grow further, but the increase in the final cost of a car will not be sharp, within 3-4%. Artyom Khomutinnikov (Артем Хомутинников), head of new car sales at Avito (Авито), does not exclude price reductions on some models, aimed at accelerating sales of current-year cars and cutting leftover stock.
These three positions describe the same market from three angles: the floor set by the coming fee change, the dealers' need to protect margin on incoming stock, and the practical necessity of clearing cars that will age on the lot. Where the three meet, the likely path is selective discounting inside a rising average.
The five forces behind the October average
- Pre-hike demand pull: buyers accelerated purchases ahead of the expected recycling fee revision and VAT increase.
- Incentive withdrawal: brands wound down discounts and cut credit subsidisation programmes, lifting transaction prices toward list.
- Model shortages: deficits across the Jetour line-up, individual Geely and Chery models and parallel-imported Mitsubishi, BMW X6 and X7 and Skoda Kodiaq removed discountable stock.
- Mix shift: a larger share of expensive models, in parallel import and Chinese line-ups, raised the weighted basket.
- Substitution into used cars: buyers priced out of new metal bid up the secondary market to its own record.
Reading the records against a constrained year
The October records should not be mistaken for a booming market. They arrived in a year when demand was held back by expensive credit and when monthly sales only returned to the level of November 2024 in the autumn rush. What the records measure is not prosperity but urgency: a market compressing a quarter of decisions into one month because the rules of pricing were about to change.
That distinction matters for 2026. A demand spike borrowed from future months leaves a hole behind it, and a price floor set by a fee change does not disappear when the hype does. The average price printed in October becomes the base from which the next year's discounts, if any, will be counted.
What the record month changed for the buyer
For the household deciding on a car in November 2025, the October record translates into three practical changes. First, the trade-in calculation: with a spread of more than 2 million roubles between the average used car and the average new car, selling the old car covers a smaller share of the upgrade than a year ago, and the missing portion must come from savings or from credit — precisely the credit that stayed expensive through the year. Second, the discount hunt moved: the models where discounts still exist are the ones dealers need to clear before year-end, which is why Avito's manager speaks of selective price cuts on current-year stock rather than blanket promotions. Third, the waiting calculus changed: with a fee-driven price floor ahead, postponing a purchase no longer obviously pays, and that belief is exactly what produced the 35% October surge.
The record also redraws the boundary between the official and the parallel channel. Deficits in parallel-imported premium models — Mitsubishi, the BMW X6 and X7, the Skoda Kodiaq — mean that part of the demand once satisfied outside official dealerships now competes for official stock, and the weighted average registers that competition as price. Meanwhile shortages across the Jetour line-up and in individual Geely and Chery models show that the official channel's own growth of recent years has outrun its logistics: the brands that replaced the departed Europeans now face their own supply constraints at the very moment demand accelerates.
None of these changes is visible in a single price tag. They live in the spread between segments, in the list of deficient models and in the calendar of the coming fee change — the three coordinates that defined the Russian car market's winter of 2025.
What the methodology hides and shows
Both records deserve a caveat about measurement. A weighted average is not a price list: it moves when prices move, but also when the composition of sales moves, and October combined the two. The new-car indicator includes modifications, so a month in which buyers take richer versions of the same models registers as inflation even if every base price stands still. The used-car indicator excludes modifications and weights by model and year, which makes its record a purer signal of fleet revaluation, but also more sensitive to the age mix of cars changing hands in a rush month.
A second caveat concerns timing. Monthly averages printed in a demand spike measure the marginal transaction of that month, not the standing value of the fleet. When the spike fades, the average can settle below the record without any model becoming cheaper, simply because the basket returns to normal. That is why the ten-month averages sit visibly below the October points in both segments, and why the record should be read as the price of urgency rather than the new equilibrium price of a Russian car.
Outlook: a slow climb, not a jump
The dealer consensus of a further 3-4% by year-end implies a market that keeps climbing without another vertical month. Two developments could change that path: a return of brand-level subsidisation, which would reopen the gap between list and transaction prices, and a replenishment of the deficient models, which would restore discount competition at dealer level. Until either appears, the record set in October 2025 remains the reference point for both the new and the used market, and the 2-million-rouble spread between them remains the measure of how far the upgrade ladder has stretched.
The records carry one more, psychological effect: once an all-time high is printed, it becomes the new reference point for negotiation, so discounts in the following months will be counted from the record rather than from the old price, and the feeling of a bargain will return to showrooms faster than the prices themselves fall.
The winter of 2025 therefore opens with a market that has priced in its own future cost shock. The records are not an accident of statistics; they are the visible trace of buyers, dealers and importers all moving ahead of the same calendar date.
Just Published

European housing prices and rents

Schneider–PTC: the industrial data integration test behind the deal

Avio USA starts work on its Virginia manufacturing site

One equity market, two currency measures

Russia’s draft budget raises spending and borrowing plans

Russia Sets the 2027 Minimum Wage at 28,935 Rubles, Up 6.8%, on the Way to 35,000 by 2030
Partner news digest
 Qatar LNG expansion: readiness, financing and the production test
 Pennon’s capital plan: turning finance into better water outcomes
 Italy’s diesel relief gap: taxes, price ceilings and implementation
 EU–China hybrid trade: from understanding to measurable implementation
 Schneider–PTC: the industrial data integration test behind the deal
 IKEA’s hybrid resale model: buyback, marketplace liquidity and furniture logistics
 Banking AI beyond the ranking: capability, execution and evidence of value
 Fishing labour beyond the product label: practical protection
 Rhenus and the Middle Corridor: terminals need coordinated connections
 Royal Mail restructuring: the test is reliable delivery
 Fuel Finder on Google Maps: when price transparency becomes useful competition
 Samsung’s memory profit surge: what the preliminary record explains
Leave a comment