
Record Month After Record Month: How New Liquefaction Capacity Made the US the Swing Supplier of Global Gas
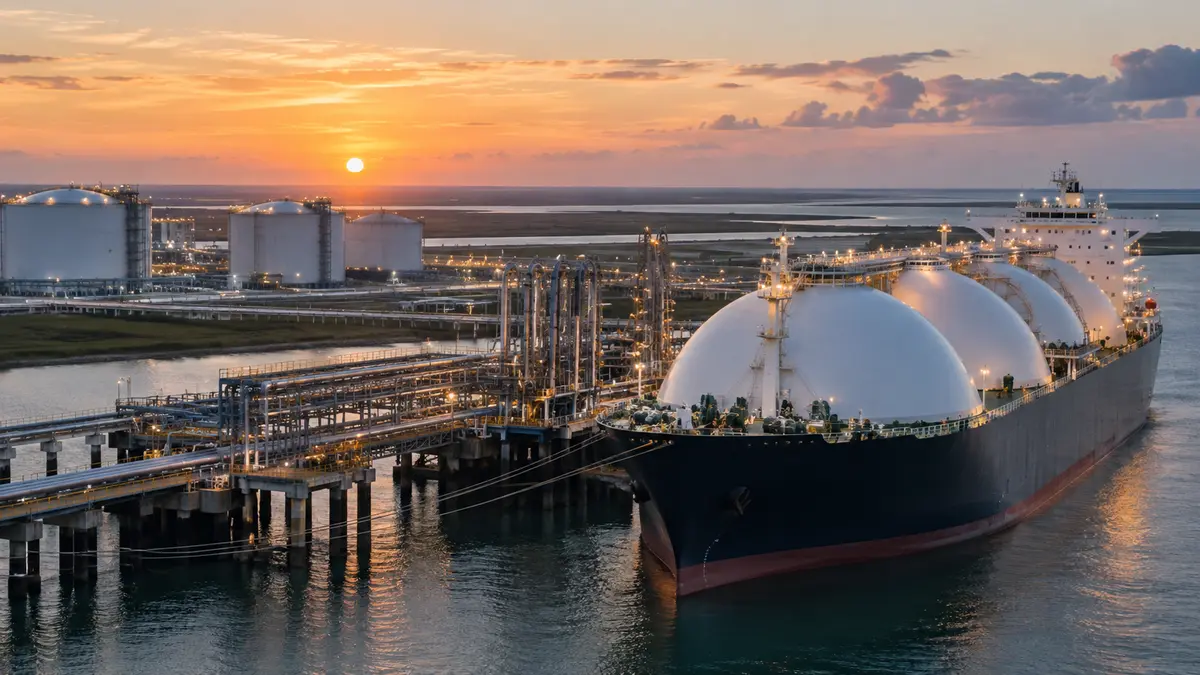
August 2025 became the strongest month in the history of the United States LNG trade: exports reached 9.33 million metric tons, beating the previous monthly record of 9.25 million tons set in April and the 9.1 million tons shipped in July. Behind the number stands a new generation of liquefaction capacity, and above all one plant on the Louisiana coast that has increased output every month since its first cargo. The record month shows how quickly the world's largest LNG exporter can move the global supply curve.
A record built plant by plant
U.S. exports of liquefied natural gas reached an all-time high in August 2025 as plants exited planned maintenance programs and Venture Global's Plaquemines facility continued to increase output, according to preliminary data from the financial firm LSEG compiled by Reuters (Рейтер). August exports totaled 9.33 million metric tons, above the 9.25 million tons of the April record and the 9.1 million tons of July. The sequence matters: a record set in spring, matched and then exceeded after the summer maintenance season ended, is the signature of a supply base that is growing faster than its own seasonal interruptions.
The United States entered 2025 already holding the title of the world's largest LNG exporter, a position it took over from the traditional heavyweights of the trade in the early 2020s after Europe's loss of pipeline gas redirected global flows. What the August data shows is that the title is not being defended on legacy assets alone: the marginal tonne of American supply now comes from plants that did not exist a year earlier.
Plaquemines: the marginal plant of the world market
Plaquemines is the second-largest LNG plant in the United States, with a capacity of 27.2 million tons per annum, and it has increased production every month since it started up in December 2024, helping the country remain the world's largest LNG exporter. In August the facility sold 1.6 million tons, or 17% of total U.S. exports, LSEG data showed. One plant, still formally under construction, supplied roughly one sixth of the monthly exports of the entire country.
The plant is not finished growing. Plaquemines remains under construction but is expected to produce from all its 18 plants in September, potentially increasing output further, according to regulatory filings. That single sentence contains the forward signal of the August record: the monthly ceiling of the U.S. export system is being redefined quarter by quarter as commissioning crews hand over trains to operators. Every additional train that enters service converts directly into cargoes that appear in ship-tracking data within weeks.
Seventeen percent and rising
The 17% share is a concentration statistic as much as a growth statistic. When a single facility provides that fraction of national exports, the reliability of the whole export system becomes partly a function of that facility's commissioning curve. The August record was therefore not only a demand story; it was a supply-availability story in which one Louisiana terminal acted as the swing unit of the global LNG market.
Where the molecules went: Europe first
Europe remained the biggest destination for U.S. LNG in August, taking 6.16 million tons, or 66% of the total, up from 5.25 million tons, or 58%, in July, LSEG ship-tracking data showed. The continental pull has a specific background: natural gas storage levels have been lower in Europe in 2025 compared with 2024, without the usual rush to stockpile the fuel before the upcoming winter period, as lower Asian imports created breathing room for European traders and governments. A market that enters autumn with thinner inventories and a calmer injection race is a market that keeps buying spot cargoes later into the season.
The European share of two thirds is also a price-arbitrage outcome. With little or no arbitrage between European and Asian gas prices in August, cargoes defaulted to the Atlantic basin route that offers the shortest voyage and the greatest flexibility. When the spread between the two benchmarks widens, the same fleet re-orients within weeks; the November 2024 pattern, when nearly seven of every ten U.S. cargoes headed to Europe on a two-year price high, is the precedent that traders remember.
The price map that steers cargoes
European gas prices fell in August to $11.13 per million British thermal units at the Title Transfer Facility hub, down from $11.56 per mmBtu in July, according to LSEG data. In Asia, the benchmark Japan Korea Marker fell to $11.63 per mmBtu from $12.18 per mmBtu over the same period. A half-dollar of convergence between the two benchmarks is small in absolute terms and decisive in cargo economics: it is the difference that decides whether a flexible cargo from the Gulf coast sails east or west.
Exports to Asia declined slightly during August to 1.47 million tons, down from 1.8 million tons in July. The Asian retreat of the summer of 2025 is the mirror image of the European advance, and together the two flows illustrate the defining feature of the American export model: flexibility. U.S. cargoes are not contracted to a fixed destination in the way legacy pipeline molecules are; they follow the spread, and the monthly destination mix is the visible trace of that behaviour.
Egypt: a structural new buyer
The most instructive line in the August dataset is the Egyptian one. Egypt has been facing falling natural gas production, declining as low as 3,485 million standard cubic meters in April 2025 compared with a peak of 6,133 million standard cubic meters in March 2021. In June the country announced it would ramp up LNG imports to meet power demand. In August it bought nine cargoes totaling 0.57 million tons, or 6% of total U.S. LNG exports, against 0.59 million tons in July.
A country whose own production has halved in four years and whose summer power demand keeps rising is not a speculative buyer; it is a structural one. Egyptian demand converts a domestic generation gap into a permanent line item on the Atlantic basin supply balance, and the stability of its monthly offtake, roughly the same in July and August, is the signature of a tender-driven programme rather than opportunistic spot purchases.
Latin America and the Trinidad offset
U.S. LNG exports to Latin America fell in August to 0.69 million tons, or 7% of total exports, down from 1.03 million tons in July. The reason is regional supply, not regional demand: the area was well-supplied from Trinidad and Tobago, where the Shell- and BP-owned Atlantic LNG plant has been producing at higher rates since June, exporting 0.8 million tons in August. When a nearby baseload supplier returns to higher utilisation, the marginal U.S. cargo to the region simply does not sail.
The same logic of neighbouring supply appears on the Pacific side. Shell's LNG Canada plant at Kitimat on Canada's west coast continued to increase exports from its Train 1, with five shipments totaling 0.4 million tons in August, up from 0.3 million tons in July. Canadian volumes do not compete with U.S. cargoes in the Atlantic, but they reshape the Pacific balance into which future American growth will have to price itself.
Uncommitted cargoes and the option value
Four percent of U.S. LNG exports in August, or 0.37 million tons, left U.S. ports with no clear destination listed, signaling they were available for orders, LSEG ship-tracking data showed. Cargoes sailing without a declared destination are the physical form of optionality: molecules put on the water to be sold wherever the spread turns out to be widest. In a record month, the size of this floating option tells how much of the record was pre-sold and how much was placed into the market in real time.
What the November 2024 pattern showed
The August 2025 record has a useful predecessor in the winter of 2024-2025. In November 2024, U.S. LNG exports to Europe surged as European gas prices climbed to their highest levels in two years on fears that remaining Russian pipeline supplies to Europe would be halted or further curtailed; European prices averaged $12.90 per mmBtu that month, with the front-month contract at the Title Transfer Facility reaching 49.03 euros per MWh on November 22, equivalent to $14.97 per mmBtu. Exports to Europe reached 5.09 million tons, or 68% of the total, up from 3.65 million tons, or just under 48%, in October, while Asian offtake fell to 1.64 million tons, or 21% of exports, from 2.67 million tons, or 35%.
Two episodes, nine months apart, describe the same machine: a price shock in one basin re-routes the American fleet within a single month. The difference between November 2024 and August 2025 is the size of the fleet doing the re-routing. Plaquemines, which was awaiting its first LNG in December 2024, was by August 2025 the single largest contributor to the monthly record. The flexibility that mattered in 2022 and 2024 has acquired a materially larger physical base.
The mechanics behind the monthly ceiling
On the supply side, the November 2024 episode also documented how tightly the export system runs against its feedgas limit: U.S. LNG natural gas demand averaged 13.65 billion cubic feet per day that month, and could have been higher had Freeport LNG not experienced several outages, while top exporter Cheniere Energy was pulling over 5 bcf per day at its Sabine Pass plant for the fifth time in seven days. The export record of a given month is therefore the intersection of three curves: liquefaction availability, feedgas supply, and the destination spread. August 2025 is the month in which all three aligned upward at once.
- Record volume: 9.33 million tons in August 2025, above the April record of 9.25 million tons and July's 9.1 million tons.
- Single-plant concentration: Plaquemines supplied 1.6 million tons, 17% of national exports, from a facility still under construction.
- Destination mix: Europe 66%, Asia down to 1.47 million tons, Egypt steady at about 0.57-0.59 million tons per month.
- Regional offsets: Atlantic LNG in Trinidad and Tobago and LNG Canada Train 1 both raised output, displacing U.S. cargoes in their neighbourhoods.
- Optionality afloat: 0.37 million tons, 4% of exports, sailed without a declared destination.
The geography of the new export base
The physical map of the American record is concentrated on the Gulf coast. The November 2024 data showed the system running at its feedgas limit with Cheniere Energy pulling over 5 billion cubic feet per day at Sabine Pass in Louisiana and Freeport LNG losing volume to outages; the August 2025 data show the same coast with a new giant in service. Plaquemines sits in the Pelican state alongside the legacy plants, and Cheniere's midscale expansion adds trains to the same cluster. Concentration of this kind is what allows a single commissioning schedule to move a national export statistic by double-digit percentages within a year.
The Pacific counterpart is younger and smaller but strategically distinct. Shell's Train 1 at Kitimat, on Canada's west coast, shipped five cargoes in August, and its ramp-up inserts a new Pacific supplier into the basin that American growth must eventually price against. For now the two coasts serve different halves of the world map; the August destination mix, with Europe at 66% and Asia retreating, shows which half absorbed the increment.
A supply-led record in a soft price tape
One feature of the August dataset deserves emphasis: the record was set while prices fell in both benchmark basins. European gas at $11.13 per mmBtu and the Japan Korea Marker at $11.63 per mmBtu were both lower than in July, which means the additional tonnes were absorbed without scarcity pricing. A record accompanied by falling prices is a supply-led record: the market took the extra volume because it was offered, not because buyers competed for it. The contrast with November 2024, when a two-year price high pulled cargoes across the Atlantic, marks the difference between a demand-shock month and a capacity-delivery month.
The policy implication is asymmetric. In a supply-led regime, the binding question for exporters is not whether the world wants the molecules but whether the destination spread covers the voyage; in a demand-shock regime, the binding question is the opposite. August 2025 belongs to the first regime, and the floating optionality of 0.37 million tons of uncommitted cargoes is the market's way of keeping the second regime available.
Signals to watch
Three markers will define whether August 2025 was a peak or a step. The first is the commissioning schedule of the remaining Plaquemines trains: full operation of all 18 units would lift the monthly ceiling again without any new investment decision. The second is the Europe-Asia spread into the 2025-2026 winter: a widening spread re-routes the fleet east-to-west or west-to-east and decides which basin absorbs the incremental tonnes. The third is the behaviour of structural buyers such as Egypt, whose tender programmes convert domestic production decline into durable Atlantic demand. A fourth, quieter marker is the maintenance calendar of the legacy plants: the August record was partly a story of outages ending, and the next maintenance season will test how much of the record was structural.
The August number will eventually be revised, as preliminary LSEG data always is. The direction will not: the United States has turned liquefaction capacity into the swing factor of the global gas market, and each new record month measures how much swing the system has left to give.
Just Published

European housing prices and rents

Schneider–PTC: the industrial data integration test behind the deal

Avio USA starts work on its Virginia manufacturing site

One equity market, two currency measures

Russia’s draft budget raises spending and borrowing plans

Russia Sets the 2027 Minimum Wage at 28,935 Rubles, Up 6.8%, on the Way to 35,000 by 2030
Partner news digest
 Qatar LNG expansion: readiness, financing and the production test
 Pennon’s capital plan: turning finance into better water outcomes
 Italy’s diesel relief gap: taxes, price ceilings and implementation
 EU–China hybrid trade: from understanding to measurable implementation
 Schneider–PTC: the industrial data integration test behind the deal
 IKEA’s hybrid resale model: buyback, marketplace liquidity and furniture logistics
 Banking AI beyond the ranking: capability, execution and evidence of value
 Fishing labour beyond the product label: practical protection
 Rhenus and the Middle Corridor: terminals need coordinated connections
 Royal Mail restructuring: the test is reliable delivery
 Fuel Finder on Google Maps: when price transparency becomes useful competition
 Samsung’s memory profit surge: what the preliminary record explains
Leave a comment