
Russia's Pharmacy Chains Return to Deals: How the Top 20 Took Two-Thirds of the Market
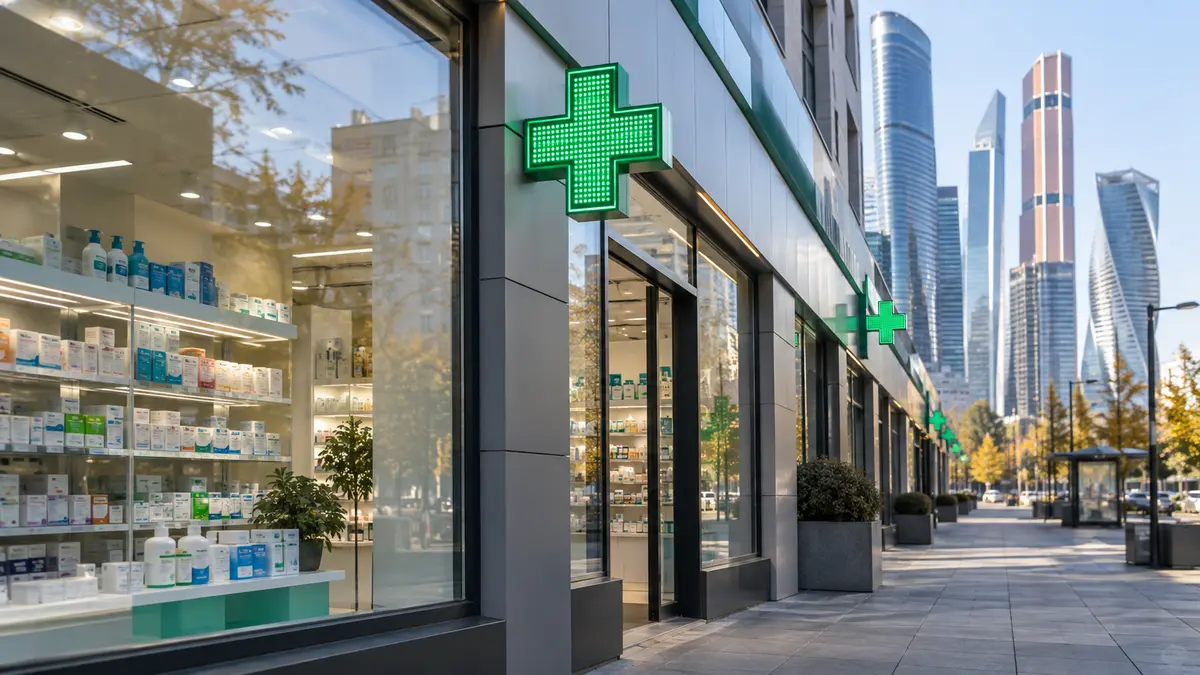
Russia's pharmacy retail market entered the second half of 2024 more concentrated than at any point since the pandemic: the top 20 chains took 66.4% of sales, up 3.2 percentage points year on year, according to DSM Group data reviewed by Kommersant. The same chains operate almost 41,000 of the country's 82,000 pharmacies, and a fresh wave of acquisitions — from Rigla's purchase of two Nizhny Novgorod chains to Neo-Pharm's takeover of Aptechnye Traditsii — shows that consolidation, not organic expansion alone, has become the main route to scale in Russia.
The two-thirds market
The commercial pharmacy market grew 17% in value terms in January-June 2024, to 980 billion roubles, while volume grew by a marginal 0.7%. Inside that market the top 20 chains grew 25%, and it is precisely this gap between chain growth and market growth that moved the concentration needle: the top 20's combined share of retail pharmaceutical turnover rose from 63.2% in 2023 to 66.4% in the first half of 2024. The chains behind that figure operate 40,860 pharmacies, against 38,530 at the end of 2023, while the national count of operating pharmacies reached 82,000, up 3,000 in six months.
The arithmetic describes a market in which half of all stores already generate two-thirds of all revenue. For manufacturers, that geography matters commercially: marketing contracts, bonus schemes and listing terms are negotiated with a shrinking number of counterparties, and a chain's position in the top ranking is itself an asset that unlocks better commercial terms.
The race for first place
The concentration story has a duel at its centre. Rigla, part of Vadim Yakunin's Protek group, and April, the Krasnodar-based network of Vadim Anisimov, spent the first half of 2024 exchanging the lead. April added 593 pharmacies in six months and closed the gap to Rigla, which added 321; Samara-based Vita came third on openings with 228. Measured by second-quarter sales, April took first place with a 9.77% share against Rigla's 9.24%, while over the half-year as a whole the gap between the two leaders narrowed to 0.39 of a percentage point.
Sergey Shulyak, chief executive of DSM Group, reads the duel as an accelerator for the whole market: the race for first place pushes players to grow more aggressively, and organic growth alone can no longer hold the positions that chains need in order to win favourable marketing contracts and bonuses from drug manufacturers. That sentence is the analytical core of the half-year: when scale determines commercial terms, M&A stops being opportunistic and becomes structural.
The deal wave returns
DSM Group's half-year review records a clear return of consolidation deals after the pause of the pandemic years and the uncertainty that followed 2022. The transactions of the first half and early August 2024 form a compact list:
- Rigla confirmed in early August the purchase of the Nizhny Novgorod chains Aptechestvo and Farmani, 375 pharmacies across eight regions; after the deal Rigla grows to about 4,800 pharmacies and a 9.6% share of the retail pharmaceutical market.
- Moscow's Neo-Pharm bought the Aptechnye Traditsii network of almost 100 pharmacies, yet kept its seventh place in the chains ranking.
- BSS absorbed Murmansk Farmatsiya, a network of 40 branches.
- Aptechnaya Set 36.6 acquired a small four-store network in Ramenskoye, Moscow region, operating under the Eksfarm and Vitafarm brands.
- In the opposite direction, Monastyrev.rf put 70 pharmacies up for sale — 10 in Moscow and the region, 2 in Novosibirsk and 56 in Khabarovsk — citing financial difficulties and a decision to concentrate on its home Primorsky Krai.
The list shows both directions of the same process: chains with access to capital buy scale, while overextended regional players sell assets to defend their core geography. Boris Popov, chief executive of Rigla, says the company reactivated its M&A work in 2023 after a period of general uncertainty in the pharmaceutical market caused by the pandemic and the political and economic situation, and that it now sees increased reciprocal interest from market participants who want to sell their businesses.
Why sellers walked back to the table
One specific incentive explains part of the timing. From 2025 the personal income tax exemption applied to proceeds from a business sale above 50 million roubles is cancelled, Popov notes, and that change pushes owners who were already considering an exit to close transactions in 2024 rather than later. Shulyak confirms the supply side: offers to sell from small networks have become more numerous.
The mechanism is worth stating plainly because it shapes the deal calendar. A tax exemption with an expiry date converts a latent supply of family-owned chains into an active one; buyers with scale economics and cheaper capital then absorb that supply at a moment when sellers are motivated by the clock rather than by price alone. The result is a concentration spike that is partly fiscal in origin.
Organic growth: building into new housing
Consolidation did not replace openings. The national pharmacy count rose by 3,000 in six months, and Anton Belykh, chief executive of DNA Realty, describes where the new stores appear: large federal pharma retailers expand through the active commissioning of new residential complexes in which commercial space for a pharmacy is provided, often signing lease agreements with property owners while the building is still under construction.
Popov names the underlying reason chains keep opening stores: market growth that increases profit. He also names the brakes — rising rent costs and higher staff wages. Belykh quantifies the first: rents for pharmacy premises rose by an average of 10-15% between June 2023 and the summer of 2024. In a market where volume growth is close to zero, rent and payroll inflation is absorbed either by margin or by price, and chains with denser networks absorb it better than independents.
What powered the 17 percent
DSM Group attributes the first-half demand picture to two factors: the return of seasonal morbidity from acute respiratory infections and influenza, with its peak in January and February, and inflation reflected in sales values. By March 2024, the agency notes, pharmacy consumption had returned to habitual levels, and the subsequent dynamics were driven mainly by price factors. That sequence — a volume spike early in the year, then a price-driven value trend — is exactly what a 17% value growth against 0.7% volume growth looks like from inside the data.
For chains, the mix matters. Value growth without volume growth rewards operators that can negotiate purchase prices, manage private-label share and hold promotional terms with manufacturers; it punishes operators whose only lever is footfall. This is another channel through which concentration reinforces itself.
The online channel loses its multiple
The half-year also marked a normalisation of pharmacy e-commerce. After the multiple-fold growth of 2022, the increase in booking volumes for medicines and parapharmacy from 2023 onwards became comparable with the growth of the pharmacy market as a whole: in the first half of 2024 pharmacy e-commerce grew 28%, only 11 percentage points above the dynamics of the commercial segment. The segment remains interesting to its participants, DSM Group notes, and the number of players presented in its online ranking keeps increasing — but the era in which online grew several times faster than offline is over, which removes one argument for staying small and digital-first.
The full-year picture: 2.85 trillion roubles
The half-year trends were confirmed by the annual outcome. According to DSM Group's report on the Russian pharmaceutical market in 2024, the total market grew 10% to 2.85 trillion roubles, with private demand in the pharmacy segment as the main driver. Pharmacy sales grew 13.8%, lifting the segment to 4.4 billion packs, or 1.635 trillion roubles; Shulyak explains the additional growth by the high incidence of seasonal respiratory infections and influenza at the start of 2024, noting that from March consumption returned to habitual levels and price factors took over.
The state segment grew more slowly. Hospital procurement financing rose 9%, to 438 million packs worth 503 billion roubles, with a significant contribution from the federal oncology programme, which was executed in full at 146.3 billion roubles. The restrained dynamics of the state segment, the report explains, stem from the limited possibility of indexing prices, since most of the drugs concerned belong to the vital and essential medicines list and manufacturers must agree their prices with the Health Ministry.
The state segment and its price ceiling
The price-ceiling mechanism has a visible side effect. Yuri Zhulyov, co-chairman of the All-Russian Union of Patients, describes interruptions in the supply of drugs within the high-cost nosologies programme and in the regional benefit segment, linking them to budget shortfalls on one side and manufacturers' attempts to raise the price of individual drugs on the other. In other words, the same regulated price list that keeps state procurement cheap also produces gaps that the commercial segment then absorbs — a transfer of demand from the state channel to the pharmacy shelf that supports chain revenue.
Three forecasts for 2025
DSM Group expects the total market to cross 3 trillion roubles in 2025, with planned financing of state health programmes and national projects at 1 trillion roubles and a possible 20% increase in government procurement across segments of drug provision; the state share of the market could rise to 36%, while the commercial market grows 9-10%, in line with inflation. Alexey Torgov, deputy chief executive for corporate relations at BIOCAD, expects a year closer to 2024: retail up about 15%, government procurement up a modest 5% — with the federal benefit contributing about 5%, the regional benefit 5% and the hospital segment 1-3% — and a long-term deceleration of market growth to 5-6% in 2025-2028. Alexander Monastyrev, owner of the Monastyrev network, adds a demand-side argument: the market can grow on the back of rising interest of Russian citizens in complex treatment.
Three forecasts, one common feature: none of them assumes a return of volume-driven expansion. Whether the market adds 5% or 15% in value, the distribution of that value will keep shifting towards the chains that control shelves, logistics and manufacturer terms.
What consolidation changes for the market
Consolidation of this speed changes three things at once. First, the commercial dialogue: with two-thirds of turnover inside the top 20, manufacturers negotiate listing and bonus terms with a counterparty group small enough to coordinate. Second, regional structure: the exit of overextended players such as Monastyrev.rf from distant regions and the entry of federal chains into new residential districts redraw the map of who serves which neighbourhood. Third, the consumer price line: in a market where value grows on prices while volume stands still, the purchasing leverage of large chains is the main force that can hold shelf prices below the inflation of manufacturers' terms.
The geography of openings and exits
The half-year map of transactions is also a map of regional economics. The buyers cluster where capital and logistics are cheapest: Moscow-based Neo-Pharm absorbing a hundred-store network, a federal chain taking 375 pharmacies across eight regions from Nizhny Novgorod, a Murmansk network of 40 branches joining BSS. The sellers cluster where expansion stopped paying: Monastyrev.rf leaving Moscow, Novosibirsk and Khabarovsk to defend Primorsky Krai is the clearest illustration of a regional operator recalculating the cost of distance. Between these two clusters sit the growth points described by DNA Realty — new residential districts where a pharmacy slot is part of the building economics from the design stage.
That geography produces a second-order effect. When a federal chain enters a district through a lease signed at the construction stage, it acquires a location that an independent competitor cannot bid for later, because the space was committed before it existed on the market. Consolidation therefore compounds: today's deal flow reallocates existing stores, while tomorrow's openings are pre-allocated to the chains that finance residential commercial space.
The unit economics behind the deal flow
Every transaction in the list can be read through one ratio: the value of a pharmacy location against the cost of holding it. Rents for pharmacy premises rose 10-15% between June 2023 and mid-2024, staff wages rose with the labour market, and volume growth stayed at 0.7%. For an owner without scale, that combination compresses margin from both sides at once; for a chain with centralised procurement, private-label share and manufacturer bonuses, the same location remains profitable. The tax change arriving in 2025 then decides the timing of the transfer of such locations from the first group to the second.
This is why the concentration figure of 66.4% should be read as a process indicator rather than a static share. It moves because the unit economics of a single pharmacy and of a chain pharmacy diverge, and because the fiscal calendar periodically accelerates the transfer of stores between the two ownership models.
The manufacturer's side of the table
Consolidation has a mirror image on the supply side. Manufacturers negotiate marketing contracts and bonus schemes with a counterparty group that now controls two-thirds of turnover, and the ranking position of a chain is part of the price of those contracts — which is exactly why Shulyak describes the race for first place as a fight for the positions needed to obtain favourable terms from producers. For a producer such as BIOCAD, forecasting retail growth of about 15% in 2025, the practical question is how much of that growth will pass through the top 20's terms and how much will remain outside them.
The state channel adds a second negotiation layer. With most socially important drugs on the vital and essential list and prices agreed with the Health Ministry, manufacturers cannot index freely; the supply interruptions described by patient organisations in the high-cost nosologies and regional benefit segments show what happens when regulated prices meet rising costs. Chains, by contrast, price freely — and in a year when value growth came mainly from prices, that asymmetry made the commercial shelf the more attractive channel for both producers and retailers.
A watchlist for the second half of 2024
- Whether April holds its second-quarter lead in full-year data, or whether Rigla's Aptechestvo and Farmani acquisition restores the gap.
- The pipeline of announced deals closing before the 2025 change in the personal income tax exemption for sale proceeds above 50 million roubles.
- Rent and payroll inflation against near-zero volume growth, the combination that decides which independents become sellers.
- The narrowing premium of online growth over the commercial segment, and whether e-commerce rankings keep adding players.
- The recovery of state procurement in 2025 and its effect on manufacturer pricing and on the supply gaps described by patient organisations.
The first half of 2024 turned Russian pharmacy retail into a scale game played on three boards at once: openings in new housing, acquisitions of regional networks, and the fiscal calendar that decides when owners are willing to sell. The top 20's 66.4% is not the end of that process; with the tax exemption expiring and rents rising, the second half of the year had every reason to add more deals to the list.
Just Published

European housing prices and rents

Schneider–PTC: the industrial data integration test behind the deal

Avio USA starts work on its Virginia manufacturing site

One equity market, two currency measures

Russia’s draft budget raises spending and borrowing plans

Russia Sets the 2027 Minimum Wage at 28,935 Rubles, Up 6.8%, on the Way to 35,000 by 2030
Partner news digest
 Qatar LNG expansion: readiness, financing and the production test
 Pennon’s capital plan: turning finance into better water outcomes
 Italy’s diesel relief gap: taxes, price ceilings and implementation
 EU–China hybrid trade: from understanding to measurable implementation
 Schneider–PTC: the industrial data integration test behind the deal
 IKEA’s hybrid resale model: buyback, marketplace liquidity and furniture logistics
 Banking AI beyond the ranking: capability, execution and evidence of value
 Fishing labour beyond the product label: practical protection
 Rhenus and the Middle Corridor: terminals need coordinated connections
 Royal Mail restructuring: the test is reliable delivery
 Fuel Finder on Google Maps: when price transparency becomes useful competition
 Samsung’s memory profit surge: what the preliminary record explains
Leave a comment