
Russia's Cement Market Opens 2026 With Its Weakest Month in Over 15 Years
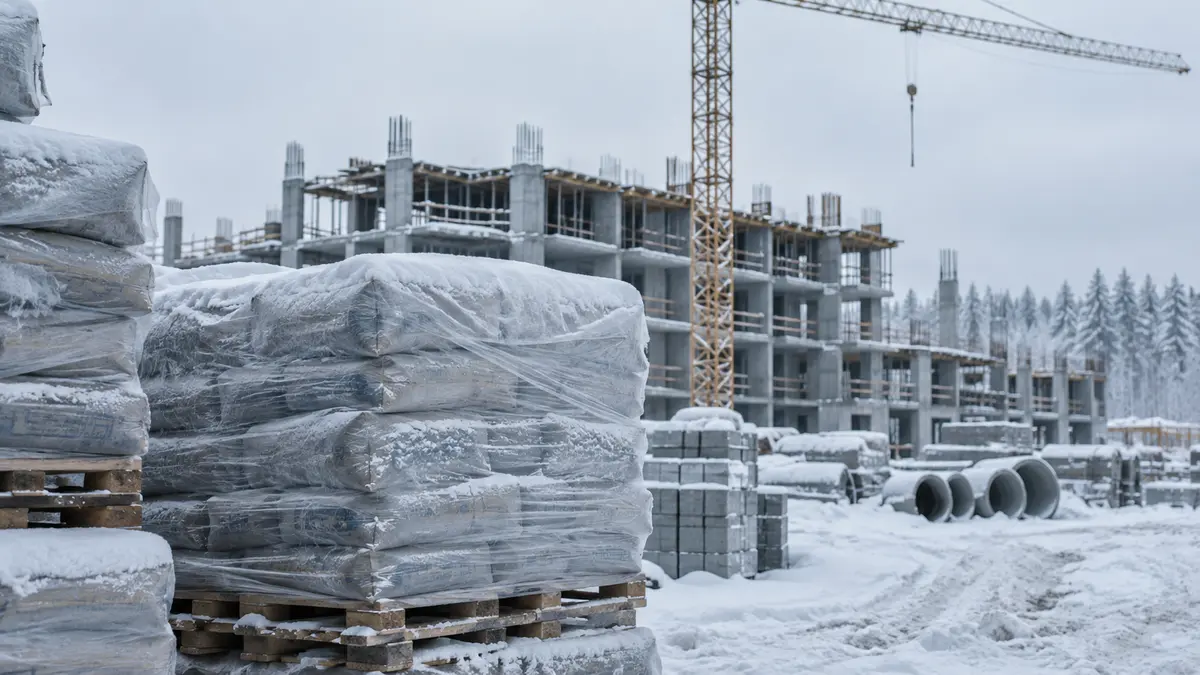
Cement consumption in Russia may fall by 20-25% year on year in January 2026, the industry association Soyuzcement (Союзцемент) estimates, with shipments at their lowest in more than 15 years. Frost and record snowfalls across most of the country stopped concreting and other site works, layering a weather shock on top of a broader construction slowdown.
An anti-record for shipments
By early February, Soyuzcement said, the market had set an anti-record for sales. The consulting company SMPRO (СМПРО) expects January consumption to drop by 30% year on year, which would make it the weakest month since 2010. The largest producer, Cemros (Цемрос), speaks of a 25% fall and shipment volumes comparable to the crisis years of 2008-2009, with the most alarming situation in Siberia, the Urals, the North Caucasus and the south of the country.
The January drop substantially exceeds last year's decline. For the full year 2025, consumption contracted by 9% year on year and by 2.9% in December, according to Soyuzcement data. About half of the January demand decrease is attributed by the association to weather: cold and heavy snowfalls almost nationwide.
Weather met an already weak construction cycle
The climatic factor is confirmed by market participants. Evgeny Vysotsky (Евгений Высоцкий), executive director of SMPRO, points to the weather effect, and the meteorological service of Lomonosov Moscow State University previously noted that January in Moscow became the snowiest in the last 203 years. Hussein Pliev (Хусейн Плиев), chief executive of Smart Ingenirs (Смарт Инжинирс), says cold and precipitation are slowing construction tempos in most regions: not a full stop, but a significant deceleration and higher costs. Alexander Ruchiev (Александр Ручьев), president of Osnova (Основа), adds that below minus 15 degrees and under heavy snowfall concrete works are not performed at all, and snowfalls can disrupt concrete delivery logistics and break the continuous pouring cycle.
Other building materials feel the same frost
Cement is not the only segment of the building materials market facing a slump. Vladimir Markov (Владимир Марков), chief executive of TechnoNICOL (ТехноНИКОЛЬ), also reports lower January demand for waterproofing and roofing materials, although December sales had grown. Works on external walls and internal slabs also stop, Ruchiev notes, if a closed thermal contour or heat supply is not secured.
What the industry watches next
- Whether the weather-driven part of the January gap closes in spring shipments.
- The trajectory of housing starts: the negative trend in construction has continued since spring 2025.
- Full-year 2026 consumption, which SMPRO does not exclude may shrink by 20% year on year.
- Macro factors, on which Soyuzcement says much will depend for the rest of the year.
January is traditionally a period of low cement demand: Pliev calls it the month of minimal construction activity in Moscow and the Moscow region, shorter in the south and longer in the north and Siberia. Winter consumption lags summer levels by two to three times on average, Vysotsky says. The question for 2026 is how much of January's anti-record was weather, and how much was the construction cycle itself.
Just Published

European housing prices and rents

Schneider–PTC: the industrial data integration test behind the deal

Avio USA starts work on its Virginia manufacturing site

One equity market, two currency measures

Russia’s draft budget raises spending and borrowing plans

Russia Sets the 2027 Minimum Wage at 28,935 Rubles, Up 6.8%, on the Way to 35,000 by 2030
Partner news digest
 Qatar LNG expansion: readiness, financing and the production test
 Pennon’s capital plan: turning finance into better water outcomes
 Italy’s diesel relief gap: taxes, price ceilings and implementation
 EU–China hybrid trade: from understanding to measurable implementation
 Schneider–PTC: the industrial data integration test behind the deal
 IKEA’s hybrid resale model: buyback, marketplace liquidity and furniture logistics
 Banking AI beyond the ranking: capability, execution and evidence of value
 Fishing labour beyond the product label: practical protection
 Rhenus and the Middle Corridor: terminals need coordinated connections
 Royal Mail restructuring: the test is reliable delivery
 Fuel Finder on Google Maps: when price transparency becomes useful competition
 Samsung’s memory profit surge: what the preliminary record explains
Leave a comment